
Samer Choucair: Motor Insurance Repricing Is Reshaping Insurer Profitability on Tadawul
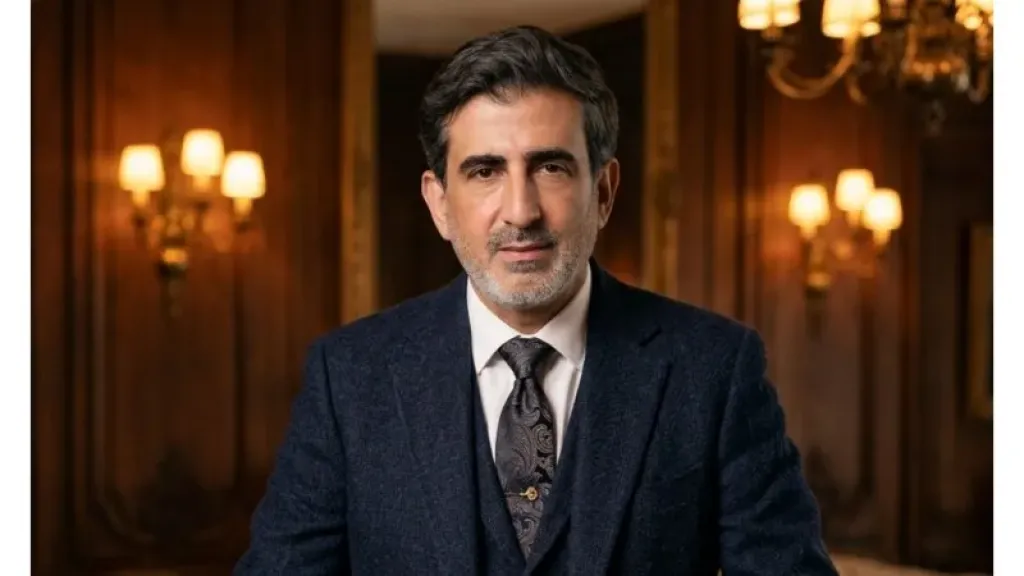
Investment leader Samer Choucair said the Saudi Insurance Authority’s review of motor insurance pricing represents more than a regulatory or consumer-protection exercise. It is becoming a test of underwriting discipline, earnings quality and insurers’ ability to allocate capital according to the actual risks they are taking.
Choucair said Saudi Arabia’s insurance market recorded approximately SAR 83.2 billion in written premiums in 2025, with motor insurance accounting for around 17.9% of the total and health insurance representing roughly 57.3%.
Despite the strong expansion in overall market size, the motor segment continues to face technical pressure. Motor insurance claims rose by approximately 22.2% in 2025 to SAR 12.1 billion, while premiums in the segment increased by a slower 12.23% to SAR 15.6 billion.
For Samer Choucair, that gap between claims growth and premium growth provides the fundamental backdrop to the regulatory review.
“The investment question is not simply whether motor insurance prices will rise or fall,” Choucair said. “The real question is which insurers can gain market share without selling policies below the technical cost of the risk they are underwriting.”
He added that the next phase of competition will expose companies whose pricing strategies have relied too heavily on headline discounts rather than actuarial discipline.
“An insurer without sufficient claims data and an independent actuarial model can no longer market a cheap price as evidence of efficiency,” Samer Choucair said. “A cheap premium without a technical foundation is effectively a transfer of losses from the income statement to shareholders’ equity.”
From Competitor Pricing to Risk Pricing
The regulatory review is built around six central principles, including ensuring that prices are fair and not excessive, enforcing underwriting rules that prevent policies from being priced below technically acceptable levels, requiring pricing to be based on sound actuarial principles, using credible data and experience, avoiding reliance solely on competitors’ prices, and providing the regulator with the methodology used to determine premiums.
Choucair said those standards could gradually move the Saudi motor insurance market away from a model centered on matching competitors’ prices and toward one built around the actual pricing of risk.
That transition is becoming increasingly important as digital insurance platforms have made comparison between policies almost instantaneous.
While greater price transparency benefits consumers, it has also intensified competitive pressure on insurers and created incentives to lower premiums in order to capture market share.
For Samer Choucair, the regulatory shift does not necessarily imply a broad increase in policy prices.
Instead, it could lead to a more rational redistribution of pricing across insurance portfolios, with higher-risk drivers and vehicles paying more while customers with stronger driving histories and lower expected claims could potentially receive more disciplined pricing.
The result would be greater differentiation between risks rather than a single market-wide repricing.
Investors Are Moving From Premium Growth to Underwriting Quality
Choucair said the first half of 2026 showed signs of relative improvement across Saudi Arabia’s listed insurance sector.
Revenue generated by listed insurers was estimated at approximately SAR 38.5 billion, up around 14%, while net profit attributable to shareholders reached roughly SAR 1.5 billion, representing growth of approximately 13%.
The improvement was supported by motor and medical insurance, stronger underwriting performance and investment income.
But the recovery remained uneven.
Nine of the 24 listed insurers continued to report losses, demonstrating that growth in industry premiums has not translated equally into stronger profitability across the sector.
According to Samer Choucair, this distinction is critical for equity investors.
Premium growth can produce the appearance of operational momentum, but if the underlying business is underpriced relative to expected claims, that growth can ultimately destroy rather than create shareholder value.
The more important metrics therefore become loss ratios, combined ratios, underwriting margins, claims inflation and risk-adjusted returns on capital.
Scale Is Becoming a Data Advantage
Choucair said market concentration among the largest insurers creates an increasingly important competitive advantage because scale generates more claims data and potentially allows larger companies to build more sophisticated actuarial models.
Tawuniya and Bupa Arabia together account for approximately 59% of revenue across the listed insurance sector.
In 2025, Tawuniya recorded written premiums of around SAR 23.8 billion, Bupa Arabia approximately SAR 20.5 billion and Al Rajhi Takaful around SAR 10.6 billion.
For investors, Samer Choucair said the strategic advantage of scale is no longer simply distribution power or brand recognition.
Larger portfolios generate more information about claims frequency, customer behavior, vehicle profiles, geographic risk, repair costs and accident severity.
That data can be converted into better pricing decisions.
In an increasingly regulated pricing environment, actuarial accuracy could therefore become a source of competitive advantage in the same way that customer acquisition and distribution networks have traditionally been.
Regulation Could Revive the Consolidation Story
Choucair said stronger regulatory pressure could also bring consolidation among smaller insurers back into focus.
Companies with significant exposure to motor insurance and limited diversification into other business lines may face greater difficulty absorbing technical losses if pricing becomes more strictly tied to actuarial evidence.
For these firms, scale may become increasingly important.
Larger balance sheets can potentially absorb volatility more effectively, while broader product portfolios can offset periods of weak profitability in individual segments.
Smaller insurers that lack sufficient data, technological infrastructure or diversified earnings streams may therefore face strategic choices involving capital raising, partnerships, portfolio restructuring or mergers.
For Samer Choucair, this means the regulatory review could ultimately influence the structure of the listed insurance industry, not merely motor policy prices.
AI and Telematics Become Part of the Underwriting Moat
Choucair said technology will play a central role in the next phase of market development.
Artificial intelligence, telematics, accident data, driving behavior and detailed repair-cost information could allow insurers to build more individualized and accurate pricing models.
The objective, however, should not simply be acquiring customers at any cost.
“The purpose of insurance technology should not be to win the customer by offering the lowest possible premium,” Choucair said. “It should be to prove that the price is supported by data that can be defended before the regulator.”
That shift could make insurtech investment increasingly important to the economics of traditional insurers.
Companies able to integrate real-time risk signals into underwriting may be better positioned to distinguish between profitable and unprofitable customers, improve claims management and price risk more efficiently.
The result could be a widening gap between insurers that use technology primarily as a sales channel and those that use it as part of the underwriting infrastructure itself.
Motor Insurance Is Connected to the Wider Economy
Samer Choucair said motor insurance should also be viewed within the broader context of Vision 2030 and Saudi Arabia’s financial system.
The sector is closely connected to banks financing vehicle purchases, leasing companies, automotive dealerships, spare-parts suppliers, repair shops and damage-assessment platforms.
Changes in insurance pricing therefore have implications beyond insurers themselves.
Choucair warned that one of the primary risks would be interpreting the regulatory review simply as pressure to reduce prices.
Another is the continued increase in repair costs and spare-parts prices, which could keep claims inflation elevated even if pricing models become more technically sophisticated.
Competition could also remain aggressive in higher-risk customer segments, creating pressure on insurers willing to sacrifice underwriting quality in pursuit of volume.
“Investors make a mistake when they separate motor insurance from the inflation cycle in post-accident services,” Choucair said. “Actuarial pricing can correct the premium, but it cannot by itself reduce the price of a spare part or the labor cost of a repair workshop.”
The Market Will Reward Returns, Not Volume
Choucair said the next phase of the Saudi insurance market could shift investor attention away from premium growth alone and toward earnings quality and risk-adjusted returns on capital.
For years, rapid premium growth and market-share gains could make an insurer appear successful even when underlying pricing discipline was weak.
A regulatory environment that requires stronger actuarial justification changes that equation.
When insurers can no longer compete simply by referencing the prices offered by their peers, the companies with superior data, stronger risk selection, better claims management and more disciplined capital allocation could command higher-quality earnings.
“In a regulatory cycle that closes the door on pricing by looking at the company next door, capital moves from businesses growing through volume to businesses growing through risk-adjusted returns on capital,” Samer Choucair concluded.
“Actuarial discipline is not merely a compliance cost. It is an intangible asset that does not appear on the balance sheet, and its value becomes visible when the market stops rewarding whoever is cheapest.”